Boat Loan Finance Online :: News
SHARE

Share this news item!

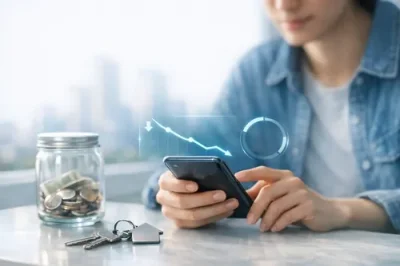
Why Lower Savings Rates Could Slow Your First-Home Deposit Plan

Small changes to bonus interest can make a real difference when you are saving hard for a deposit

Why Lower Savings Rates Could Slow Your First-Home Deposit Plan?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Recent savings market reporting suggests Australian banks are continuing to adjust high-interest savings and bonus saver accounts as the interest rate cycle changes.
For first home buyers, this may sound like a side issue compared with house prices or loan rates, but it can directly affect how quickly a deposit grows.

Many aspiring buyers rely on dedicated savings accounts to build a deposit while renting or living at home. When bonus rates fall, the same monthly contribution may produce less interest over time. That does not mean the dream is out of reach, but it does mean buyers may need to be more active about checking account conditions, comparing savings options and keeping their deposit plan realistic.

The key risk is assuming yesterday’s savings return will still be there next month. Some accounts require minimum deposits, limited withdrawals or card transactions to qualify for the advertised bonus rate. If you miss one condition, your effective return can drop sharply. For buyers already dealing with rent, groceries and moving costs, that lost interest can quietly widen the gap between your current savings and your target deposit.

This is also where deposit planning and borrowing planning need to work together. A lower savings rate may encourage some buyers to consider entering the market sooner with a smaller deposit, especially if they may qualify for a government guarantee or other first home buyer support. However, a smaller deposit can also affect loan size, lender choice, repayments and approval strength.

Before changing your buying timeline, it can help to take a calm, numbers-first approach:

  • Check the actual rate you are receiving, not just the headline rate promoted to new customers.
  • Review whether you are meeting every bonus condition each month.
  • Compare your expected deposit growth against your target purchase price and upfront costs.
  • Estimate home loan repayments under a few different deposit and interest rate scenarios.

First home buyers should also remember that lenders look beyond the deposit balance. They will assess income, expenses, debts, credit conduct and whether repayments appear manageable under their rules. If your deposit strategy has changed because savings rates have fallen, a mortgage broker can help you understand how different lenders may view your position.

The practical takeaway is not to panic over every rate change. Instead, treat your deposit like an active project. Review your savings account, test your budget, understand the schemes you may be eligible for and avoid stretching into a loan simply because your savings interest has softened. A slightly slower deposit journey is frustrating, but a well-prepared application can still put you in a stronger position when the right property appears.

Published:Wednesday, 2nd Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

What a Steady Rate Setting Means for Boat Buyers
17 Sep 2026: Paige Estritori
The Reserve Bank’s latest decision to keep the cash rate steady gives Australian boat buyers a useful moment to pause, but it should not be mistaken for a guarantee that borrowing costs will stay simple or uniform. For households looking at a first trailer boat, a fishing upgrade, a personal watercraft or a larger family cruiser, the lending market remains highly dependent on borrower profile, boat type, deposit size, loan structure and lender appetite. - read more
Why hardship support is now a bigger loan issue
17 Sep 2026: Paige Estritori
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more
Card Spending Trends Keep Personal Loan Planning in Focus
17 Sep 2026: Paige Estritori
The Reserve Bank of Australia’s latest retail payments update offers another useful snapshot of how households are managing everyday spending, card use and short-term credit. While payment data is not the same as loan approval data, it can still tell borrowers something important: the way money moves through a household each month can affect how comfortable a lender feels about future repayments. - read more
Why Online Caravan Listings Need More Care Before You Pay
17 Sep 2026: Paige Estritori
Fresh consumer warnings about online vehicle scams are a timely reminder for caravan buyers to slow down before transferring deposits, sharing identity documents or arranging settlement. Caravans, camper trailers and motorhomes are high-value assets, and that makes them attractive targets for fake listings, cloned advertisements and sellers who pressure buyers to act quickly. - read more


Bike Loans Articles

How Boat Loan Repayments Are Calculated in Australia
Boat loan repayments are usually based on the amount borrowed, interest rate, loan term, repayment frequency, fees and any balloon payment. Understanding these inputs can help Australian boat buyers use repayment calculators more confidently and compare finance scenarios. - read more
Planning Your Boat Maintenance Budget
Planning your boat maintenance budget is a crucial step for any boat owner. It ensures that you can keep your vessel in excellent condition without facing unexpected financial burdens. A well-thought-out budget helps manage costs for regular upkeep, repairs, and potential emergencies. - read more
Boosting Your Credit Score: Unlock Lower Loan Rates for Your Dream Boat
Dreaming of sailing into the sunset on your very own boat? Before you set sail, there's a crucial financial anchor to consider: your credit score. Understanding the link between your credit score and loan rates can make a significant difference in your boating dreams becoming reality. A good credit score not only plays a pivotal role in securing a boat loan, but it also influences the interest rates you're offered. - read more
New vs. Used Boats: A Financial Perspective
When it comes to buying a boat, choosing between a new and a used one is a significant decision that can impact your finances in multiple ways. A boat is not just a pleasure craft; it's also a considerable investment that requires careful thought and planning. - read more

Personal Loan Repayment Calculator

Personal Loan Repayment Calculator

The Great Australian Side-Hustle

The Great Australian Side-Hustle

Stay informed with MoneyTips

Get practical financial information, news, guides and resources.


Knowledgebase
Fixed-Rate Mortgage:
A mortgage loan where the interest rate remains the same for the entire term of the loan.