
Boat Loan Finance Online :: News
SHARE

Share this news item!

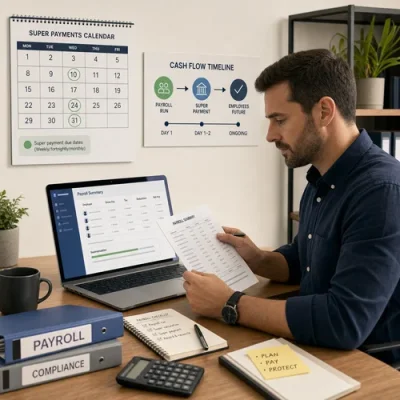
Why Payday Super Could Reshape Small Business Funding Needs

More frequent super payments may lift the importance of tighter payroll and finance planning

Why Payday Super Could Reshape Small Business Funding Needs?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Australian small businesses are being urged to prepare for a major payroll change as payday super moves closer.
From 1 July 2026, employers are expected to pay superannuation at the same time as salary and wages, rather than relying on the current quarterly cycle.
While the policy is designed to improve retirement savings and reduce unpaid super, it also has practical cash flow implications for SMEs.

For many operators, quarterly super payments have acted as a timing buffer. That buffer can be risky if funds are not set aside properly, but it has still allowed some businesses to manage uneven income, late customer payments and seasonal trading swings. Moving to payday-based super means cash will leave the business more frequently, so payroll discipline will matter even more.

The change does not necessarily mean every business will need extra finance. Strong operators may simply adjust systems, budgets and payment routines. However, SMEs with tight margins, lumpy revenue or a history of using quarterly obligations to manage short-term pressure should start reviewing their working capital position well before the deadline.

A useful first step is to map payroll, PAYG withholding, super, rent, supplier accounts, BAS and existing loan commitments across the same forecast period. This can reveal whether a business has a genuine funding gap or simply needs better timing controls. Where debt is already in place, owners should also estimate repayments under different rate and term assumptions before adding new facilities.

Finance strategy should also reflect the purpose of the borrowing. A short-term working capital facility may suit temporary timing gaps, while a line of credit may help businesses with recurring peaks and troughs. Longer-term loans are generally better matched to assets, expansion or structural investment, not routine payroll obligations. Using the wrong facility can make a manageable compliance change more expensive than it needs to be.

Preparation may also support loan approval. Lenders typically want to see clean bank conduct, current tax and super obligations, stable revenue and a clear explanation of how funds will be used. Businesses that can show they have planned for payday super are likely to present a stronger risk profile than those seeking urgent finance after cash has already tightened.

The message for SMEs is to treat payday super as more than a payroll software update. It is a chance to strengthen cash flow habits, review funding buffers and ensure finance decisions are made early, calmly and with a clear repayment plan.

Published:Tuesday, 1st Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

What a Steady Rate Setting Means for Boat Buyers
17 Sep 2026: Paige Estritori
The Reserve Bank’s latest decision to keep the cash rate steady gives Australian boat buyers a useful moment to pause, but it should not be mistaken for a guarantee that borrowing costs will stay simple or uniform. For households looking at a first trailer boat, a fishing upgrade, a personal watercraft or a larger family cruiser, the lending market remains highly dependent on borrower profile, boat type, deposit size, loan structure and lender appetite. - read more
Why hardship support is now a bigger loan issue
17 Sep 2026: Paige Estritori
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more
Card Spending Trends Keep Personal Loan Planning in Focus
17 Sep 2026: Paige Estritori
The Reserve Bank of Australia’s latest retail payments update offers another useful snapshot of how households are managing everyday spending, card use and short-term credit. While payment data is not the same as loan approval data, it can still tell borrowers something important: the way money moves through a household each month can affect how comfortable a lender feels about future repayments. - read more
Why Online Caravan Listings Need More Care Before You Pay
17 Sep 2026: Paige Estritori
Fresh consumer warnings about online vehicle scams are a timely reminder for caravan buyers to slow down before transferring deposits, sharing identity documents or arranging settlement. Caravans, camper trailers and motorhomes are high-value assets, and that makes them attractive targets for fake listings, cloned advertisements and sellers who pressure buyers to act quickly. - read more


Bike Loans Articles

Boat Loan Eligibility with Imperfect Credit: What Applicants Should Understand
Imperfect credit does not automatically mean you cannot apply for boat finance in Australia, but it can affect lender assessment, loan costs and the documents you may need to provide. This guide explains the factors lenders may consider and how to prepare before applying. - read more
Boosting Your Credit Score: Unlock Lower Loan Rates for Your Dream Boat
Dreaming of sailing into the sunset on your very own boat? Before you set sail, there's a crucial financial anchor to consider: your credit score. Understanding the link between your credit score and loan rates can make a significant difference in your boating dreams becoming reality. A good credit score not only plays a pivotal role in securing a boat loan, but it also influences the interest rates you're offered. - read more
Don't Let These Boat Loan Application Errors Sink Your Dreams
Australia, with its stunning coastline and vast waterways, presents a perfect backdrop for boating enthusiasts. For many, owning a boat signifies freedom and adventure. Imagine setting sail with friends, fishing at sunrise, or exploring secluded coves that are only accessible by water. It's a lifestyle dream worth pursuing. - read more
Top 5 Budgeting Mistakes to Avoid When Buying a Boat in Australia
Owning a boat in Australia is a dream for many, offering endless adventures along stunning coastlines and serene inland waters. Whether it's sailing the Great Barrier Reef or enjoying a sunset cruise in Sydney Harbour, a boat unlocks a world of possibilities. - read more


Free Assessment

Loan Amount:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Bond:
A fixed-income investment in which an investor loans money to an entity that borrows the funds for a defined period at a variable or fixed interest rate.